Author: Jae, PANews
For a long time, governance tokens of numerous crypto projects have been criticized by the market as "shitcoins" detached from fundamentals due to a lack of effective value-capture mechanisms. Now, as on-chain protocols gradually demonstrate real profitability, crypto assets are undergoing a structural revolution in tokenomics.
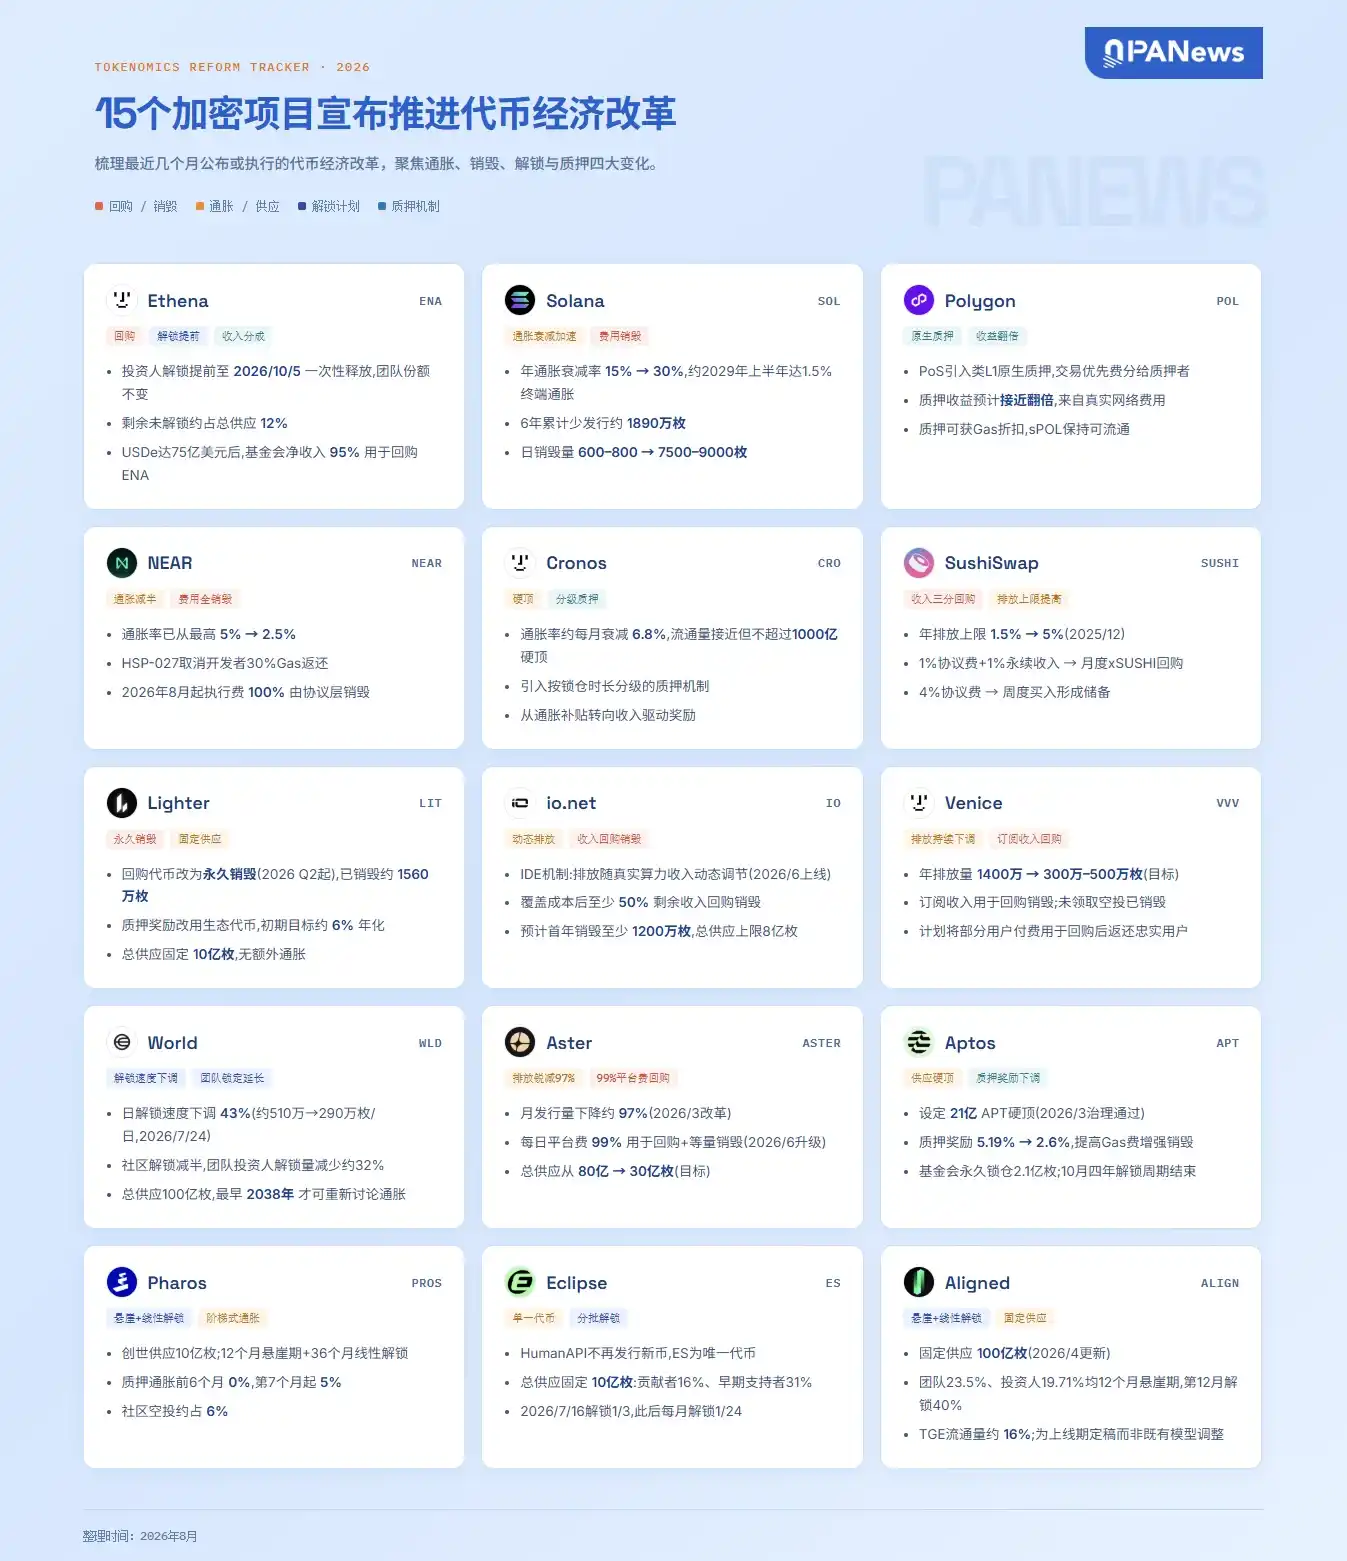
According to PANews statistics, 15 mainstream crypto projects including Ethena, Solana, and Polygon are rewriting their token economic models. From inflation reduction and buyback-and-burn to unlock schedule adjustments and staking mechanism upgrades, project teams are redesigning the supply-demand dynamics and value-capture logic of their tokens.
Meanwhile, another set of numbers more intuitively reflects this trend: according to statistics from Allium Labs, as of the end of August, the amount spent on token buybacks by crypto projects this year has reached nearly $640 million, far exceeding the $5.45 million from the same period last year and a mere $366,000 for the entire year of 2024.
This signifies that tokenomics reform is shifting from "how to issue more tokens" to "how to reduce supply, create real demand, and establish a more direct connection between protocol revenue and token value."
Reforms by 15 Projects Converge Along Four Main Paths
According to PANews statistics, over recent months, 15 well-known projects spanning public chains, DeFi, AI, and the DePIN sectors have introduced adjustments to their tokenomics through community proposals and governance votes. Their reform measures primarily extend along four paths: inflation reduction, buyback-and-burn, unlock optimization, and staking empowerment, reflecting strategic divergences in value-capture mechanisms among different types of projects.
Public Chain Layer: Curbing Inflation, Setting a Hard Cap
For public chains represented by Solana, NEAR, and Aptos, the core of reform is controlling supply and ending inflation subsidies.
-
Solana, through the SIMD-550 governance proposal, doubled its annual inflation decay rate to 30%, accelerating towards its terminal inflation rate of 1.5%, which is expected to reduce SOL issuance by nearly 18.9 million tokens over the next 6 years;
-
NEAR slashed its inflation cap by half to 2.5% and canceled the Gas subsidy returned to developers, achieving rigid protocol-level burning of the full execution fee;
-
Aptos set a hard cap on its supply, alleviating negative market expectations of "continuous significant dilution" from the supply side.
This marks a transition where infrastructure is moving from expansion subsidized by issuance to balancing supply and demand based on real on-chain demand.
Application Layer: Cash Flow Feedback
Vertical applications represented by Lighter, Aster, io.net, Venice, and SushiSwap aim to embed protocol revenue into the token's supply-demand curve.
-
Lighter and Aster convert the vast majority of platform transaction fees into buy-side pressure in the secondary market for burning, alleviating token inflation;
-
io.net and Venice pioneered the precedent of off-chain revenue feedback: io.net introduced a dynamic release mechanism tied to actual computing power revenue, using over 50% of the surplus after deducting operational costs for buyback-and-burn; Venice channels part of AI inference subscription fees into buybacks, exploring ways to translate off-chain cash flow into token value;
-
SushiSwap restructured its fee distribution matrix, allocating part of protocol fees and perpetual contract revenue to secondary market buybacks and operational treasury reserves, balancing short-term buy-side pressure and long-term funding.
Their adjustment rationale is to liberate the token from being merely a governance credential into a value carrier capable of sharing in business growth.
Unlock Side: Defusing Bombs and Smoothing the Curve
To address structural selling pressure from early-stage holdings, projects have adopted various distinctive unlock restructuring strategies.
-
Ethena chose "short-term pain over long-term pain": releasing all remaining investor allocations in a one-off event on October 5th this year, while keeping team allocations unchanged; simultaneously, it plans to initiate a 95% net revenue buyback once the USDe target scale of $7.5 billion is reached, attempting to eliminate the bearish expectations associated with long-term monthly unlocks in one go;
Related Reading: Buying Out Tokens, Starting Buybacks: Ethena's Four-Arrow Strategy, How Will ENA Play the "Value Return" Card?
-
World chose to trade time for space: reducing the daily token release rate by 43%, pushing the inflation issue back to 2038, and using a lower release rate to achieve a smoother market impact;
-
Newer projects like Aligned and Pharos proactively avoid risks from the start: establishing a 12-month cliff lockup and phased vesting schedule at the initial TGE, compressing staking inflation to zero during the cold-start period to prevent selling stampedes amid insufficient liquidity.
Staking Side: Evolving from Inflation-Subsidized Issuance to Real Yield
Polygon and Cronos are set to reconstruct their staking systems, aiming to shift the source of staking rewards from inflationary issuance to real business revenue.
-
Polygon will introduce a native staking mechanism into its PoS architecture, allocating a portion of network transaction priority fees to stakers. Staking rewards will thus be detached from inflation subsidies, instead supported by the network's real throughput, while also incorporating sPOL to release liquidity.
-
Cronos will introduce tiered staking weights mandatorily linked to lock-up durations, switching the incentive source to the ecosystem's business revenue. This aims to guide long-term capital accumulation and suppress floating supply in the secondary market.
"Duopoly" Becomes Main Force in Buybacks, But Buybacks Do Not Equal Price Appreciation
It is worth noting that over half of the 15 projects involve token buybacks or burns, which are becoming widely adopted adjustment tools.
The sharp increase in buyback scale within the crypto space this year also indicates that mainstream decentralized protocols are systematically borrowing capital allocation logic from traditional stock markets, enhancing the economic value per token unit through profit buybacks and supply cancellation. Projects with ample cash flow attempt to provide buy-side support for their protocol tokens by using protocol revenue for buybacks.
In terms of market structure, two leading protocols, Hyperliquid and pump.fun, together account for nearly 90% of the crypto project buyback volume.
Hyperliquid is the most aggressive: approximately 99% of its protocol fees are used by the Assistance Fund to buy back HYPE for permanent burning. To date, the Assistance Fund's cumulative buyback amount is around $11-13 billion, accounting for 4.7% of the total token supply. HYPE price has repeatedly hit new highs, breaking above $80. Pump.fun allocates 50% of its revenue to buyback-and-burn, having cumulatively burned about $445 million, accounting for 16.35% of the total token supply. PUMP's current market price is roughly flat compared to when the buyback started.
Bitwise CIO Matt Hougan stated that the entire crypto market is undergoing an "earnings revolution." He emphasized that the main obstacle preventing traditional mainstream capital from large-scale allocation into crypto assets has long been the inability of tokens to generate accountable cash flow returns. However, when protocols like Hyperliquid and Uniswap establish mechanisms linking network prosperity to token deflation, token holders will be able to substantially share in the growth dividends of the protocol.
Judging by market performance, the buyback mechanism indeed has positive cases showing strong performance, but a buyback itself is not a sufficient condition for determining token price.
So far, protocols like Chainlink, Jupiter, and Layerzero, which also execute buybacks, have seen their token prices fall by approximately 50%, 70%, and 45% respectively from when their buybacks started. Hyperliquid's uniqueness lies in the fact that while buying back tokens, the protocol also maintained growth, forming a positive flywheel effect, rather than simply "propping up the price with money."
Elton Shehdula, Head of Research at Allium Labs, points out: While buyback behavior can reduce circulating supply and create buy-side demand, it cannot replace organic growth in protocol revenue, nor can it guarantee long-term token appreciation.
Looking at cases like Chainlink and Jupiter, even with buybacks in place, if business growth slows or the competitive landscape worsens, token prices can still continue to decline.
Tokenomics Reform is Evolving from "Designing a Set of Rules" to "Designing a Business"
This wave of reform essentially represents crypto projects attempting to reposition the role of tokens within their business models. In the past, tokens served as fundraising tools, growth incentives, and governance credentials; now, an increasing number of projects are trying to make them the vehicle for capturing the value of protocol revenue.
However, significant issues remain: if a project cannot generate stable cash flow, the effect of buybacks may only exist at the expectation level. Deflation also does not equal value growth. If users, trading volume, and revenue continue to decline, token prices may keep weakening even as the token supply decreases.
In the future, the criteria for judging token economic models may shift from "how many are issued, unlocked, what's the APY" to indicators like "how much revenue, how is it distributed, how much is bought back, what's the net issuance, and is it sustainable."
The phenomenon where Hyperliquid and pump.fun contribute nearly 90% of buybacks also serves as a reminder to the market: the so-called "value capture transformation" remains highly concentrated, with the vast majority of projects yet to establish a link between revenue and token value.
Ultimately, every tokenomics model reform needs to be tested against the same question: does the token price increase come from a smaller supply, or from a larger pie?