Author: Wall Street News
The US August nonfarm payrolls data significantly exceeded expectations, further widening market divergence over the Fed's September policy path. The strong job growth indicates the US economy remains resilient and has led markets to reassess their expectations for further Fed rate hikes. US stocks fell on Friday, Treasury yields broadly rose, and gold came under pressure.
Data released by the US Labor Department on Friday showed that nonfarm payrolls increased by 162,000 in August, about three times the economists' forecast. The stronger-than-expected employment performance suggests the labor market has not deteriorated as significantly as markets had previously feared, further complicating the Fed's policy balancing act between employment and inflation.
Federal funds futures markets indicate that the probability of a Fed rate hike at the September 16th meeting has risen to about 60%. Previously, Fed Governor Waller signaled a preference to hold rates steady, leading to some retrenchment in market bets for a September hike.
Market reactions subsequently tilted hawkish. The three major US stock indices closed lower across the board on Friday, and US Treasury yields broadly moved higher. However, on a weekly basis, the S&P 500 and Nasdaq 100 indices still posted gains, indicating the market adjustment triggered by this employment data remains relatively limited so far.
US Treasury Yields Rise Across the Curve, Risk Assets Show No Significant Pressure Yet
Following the employment data release, US Treasuries were sold off, with yields rising broadly across maturities.
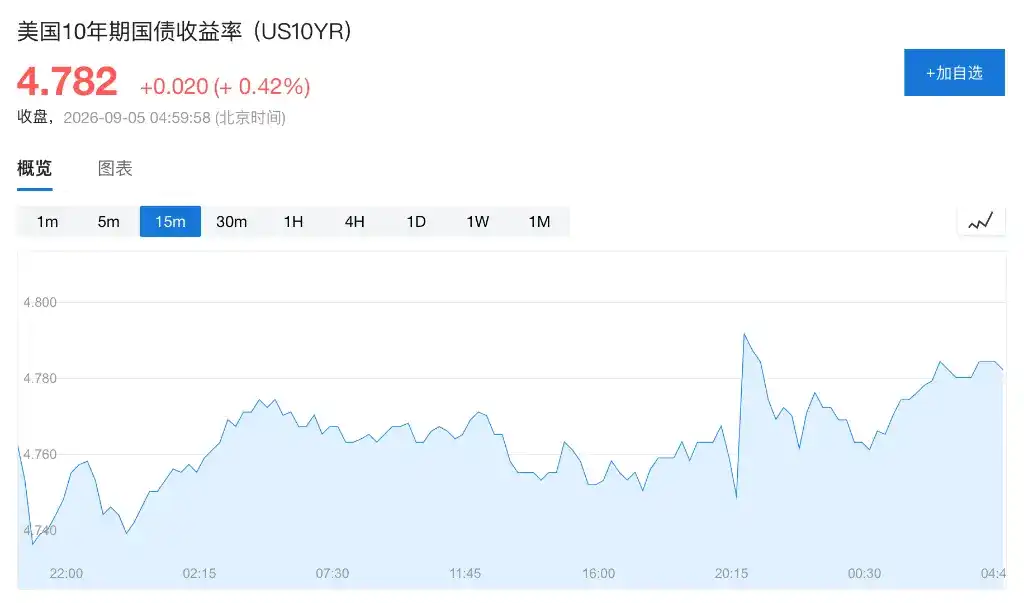
Among them, the most policy-sensitive 2-year Treasury yield rose 3.4 basis points to 4.3703%, hitting an intraday high of 4.416%, the highest since January 2025; the 10-year Treasury yield rose 2.2 basis points to 4.782%; the 30-year Treasury yield edged up 0.3 basis points to 5.246%.
However, the transmission of this bond market volatility to other risk assets remains limited. Credit spreads remain at low levels, and the cost of downside protection for risk assets is also relatively modest. JPMorgan notes that US Treasury market liquidity has deteriorated noticeably, but similar pressures have not yet appeared in stock index futures or corporate bond ETFs.
Collin Martin, Head of Fixed Income Research and Strategy at Charles Schwab, said current financial conditions remain accommodative, and credit spreads are still at exceptionally tight levels. Meanwhile, corporate earnings are growing over 20% year-over-year, and current corporate financing costs do not yet appear to pose a significant strain on businesses.
This means that, despite the employment data pushing up rate expectations, the impact of high interest rates on corporate financing and risk assets has not yet fully materialized.
AI Investment Boom Provides Support, Employment Structure Shows Divergence
The current resilience of the US economy is also linked to the ongoing boom in AI infrastructure investment.
Brad Conger, Chief Investment Officer at Hirtle & Co., stated that the contours of 'AI substitution effects' are already faintly visible in the August employment data: combined, the finance and information sectors lost 34,000 jobs, while employment in construction, manufacturing, and utilities—sectors related to data center construction, equipment supply, and power infrastructure—was notably stronger.
Economists at BNP Paribas noted in a client report that this employment report shows the US economy remains in a cyclical expansion phase, supported significantly by accommodative policies and the AI infrastructure construction boom. With labor supply constrained, the unemployment rate could continue to fall, and wages face upward pressure.
At the same time, high financing costs have not yet significantly suppressed credit expansion. JPMorgan found that, although borrowing costs have risen, US loan volumes and money creation have not contracted in sync; bank lending is still growing, and net issuance of US investment-grade corporate bonds also increased in August.
Therefore, the current US economic situation does not represent a typical 'high-interest-rates-suppress-demand' scenario. While corporate financing costs have increased, credit activity and investment demand continue to show some growth, which is also one reason why risk assets have not seen more severe adjustments in response to the hawkish-leaning employment data.
Rate Hike Expectations Intensify, CPI to Become Next Key Validation
While the nonfarm payrolls data is clearly hawkish-leaning, it is not enough to completely determine the Fed's next policy step. The market will now shift more focus towards inflation data.
Dan Suzuki, Global Investment Strategist at iCapital, warned that if interest rates rise significantly further, it could force investors to more aggressively cut risk exposure and further deteriorate market sentiment.
Sarah Hunt, Chief Market Strategist at Alpine Saxon Woods, said that compared to a weaker employment report, this data provides significantly less policy basis for the dovish camp.
Marvin Loh, Senior Macro Strategist at State Street, pointed out that Friday's employment report again shows the US economy is performing well even without structural conditions to lower unemployment. He believes the market is signaling to the Fed that it 'should hike rates' and still expects the Fed to raise rates within the year.
Greg Boutle, Head of US Equity & Derivatives Strategy at BNP Paribas, stated that with the earnings season largely over, macroeconomic data will be important variables influencing the market in the coming weeks. He believes it's appropriate to adopt a more cautious stance on stocks now, but it's not yet time for a definitive bearish view.
In his view, while Friday's nonfarm payrolls data leaned slightly hawkish, it has not fully clarified the Fed's next policy direction. The most critical variables ahead are the CPI data to be released next week, and whether the Fed will choose to hike rates before the US midterm elections.