All Metrics Smashing Records, Yet Stock Prices Plunge Across the Board

marsbitPublished on 2026-08-07Last updated on 2026-08-07

Abstract

Memory giants like Western Digital (WDC) and SanDisk (SNDK) reported blockbuster earnings in the summer of 2026, featuring毛利率 exceeding 80%, massive customer prepayments, and long-term supply agreements. Despite this seemingly perfect performance, their stocks plummeted post-earnings (WDC down 13%, SNDK down 7%), along with peers like Micron. The collapse highlights a core market rule: "good" isn't enough; results must beat already sky-high expectations. With valuations at peak "perfect asset" levels, even slightly conservative forward guidance triggered a sell-off. The market saw "peak performance" as a signal to exit. Beneath the stellar numbers, four反常 trends emerged: 1. **Financialized Pricing:** Customers provide百亿级 in upfront "interest-free deposits" to secure future capacity. 2. **Reversed Cost Curve:** Advanced DRAM (HBM4, DDR6) costs are rising per bit due to complex packaging, breaking Moore's Law. 3. **AI vs. Consumer Split:** Data center storage demand soars (+103% for SanDisk), while consumer electronics demand weakens under high costs. 4. **HDD Revival:** Hard drives, now used for AI agent context caching, see毛利率 near 55-57%. Underlying隐忧 persist. Soaring capital expenditure (CapEx) by SK Hynix and Micron risks future oversupply. Revenue growth is increasingly driven by price hikes, not surging shipment volumes (bit growth), making profits vulnerable to any price correction. In conclusion, while AI has created a long-term growth narrative, transforming s...

Storage giants have just delivered what can be described as "epic" earnings reports.

Gross margins soaring into the 80%+ "money-printing" mode, long-term take-or-pay customer agreements spanning 3-5 years, and even customers eagerly handing over tens of billions of dollars in "interest-free deposits"... If one looked solely at the financials, the semiconductor memory industry is in the midst of the most ferocious super-boom period in history.

However, the capital market's reaction has been brutally cold.

Last night, Western Digital (WDC) plummeted over 13% after earnings, SanDisk (SNDK) dropped 7%, with Micron and SK Hynix also following the decline.

The performance is dazzlingly bright, yet stock prices tumble on the news. What exactly is the logic behind this great memory market crash occurring in the summer of 2026?

01. What Killed the Stock Price is Precisely the "Flawless" Expectations

In the rulebook of the capital market, being "good" is not enough; being "better than expected" is the hard rule.

When an industry's gross margin is pushed to a historical absolute peak above 80%, the market no longer prices it as a "cyclical stock" but as a "perfect asset."

Guidance falling short of "super-high expectations": SanDisk and Western Digital's quarterly results may have crushed consensus, but even a slight hint of "conservatism" in the next quarter's guidance became the perfect excuse for funds to take profits.

Extremely crowded positioning: Over the past few quarters, the bullish news surrounding AI memory (HBM, high-capacity eSSDs, nearline HDDs) has been thoroughly priced in by all corners of the market. Any slight signal of "marginal slowdown" triggers a stampede-like retreat from the long side.

As Wall Street traders' subtext goes: The day good news materializes is the day it becomes old news.
02. Four "Anomalous" Phenomena in the Earnings Reports: This is No Longer the Familiar Memory Cycle

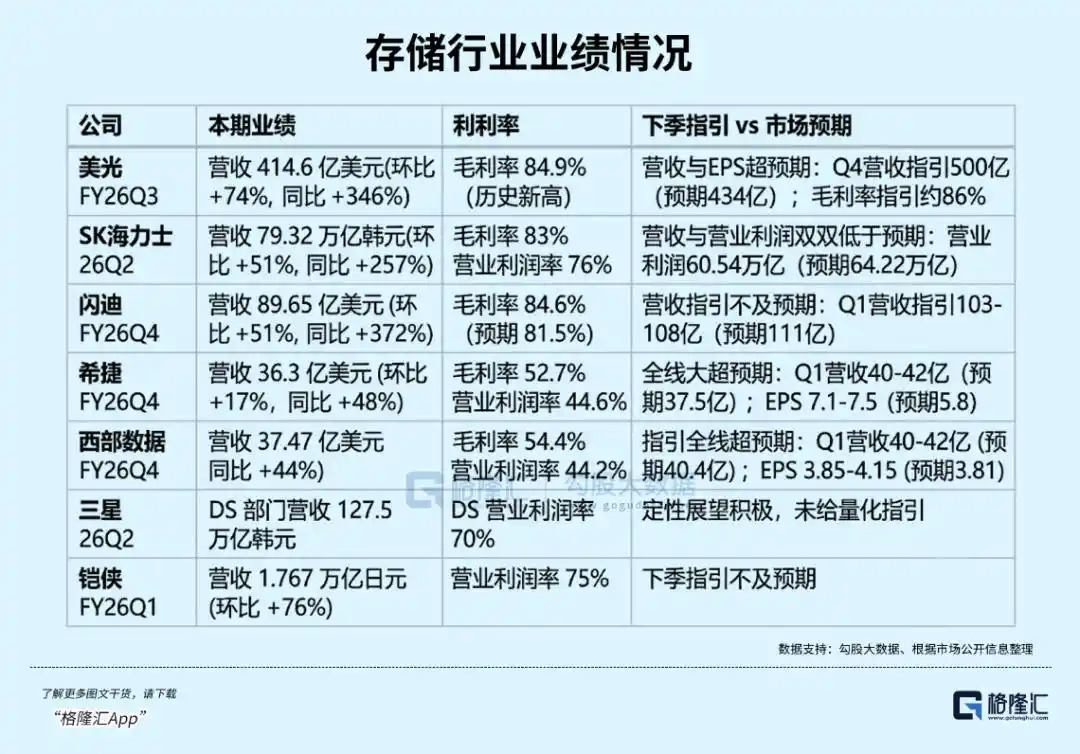
Analyzing the earnings reports from Micron, SK Hynix, SanDisk, Seagate, and Western Digital reveals that the current memory market has deviated from the traditional trajectory of Moore's Law, exhibiting four unprecedented "anomalous signals":

Customers Rushing to Offer "Interest-Free Deposits": The Financialized Pricing Mechanism

In Micron and SanDisk's reports, a phenomenon rare in semiconductor manufacturing history emerged—customer prepayments were directly classified under "financing cash flow" rather than "deferred revenue." Micron received up to $18 billion in customer cash deposits, and SanDisk secured $16.5 billion in financial guarantees.

This is essentially tens of billions of dollars in interest-free supply chain financing willingly provided by downstream industry giants to secure a "membership ticket" in future capacity allocation.

Moore's Law Completely "Broken": Cost Curve Inverts Upwards

For decades, the semiconductor industry followed "process node scaling -> cost per bit declines." However, in Micron's earnings call, management clearly stated: as DRAM advances towards HBM4/4E and high-end DDR6, the cost per bit is rising against the trend!

Complex 3D TSV packaging, stringent thermal dissipation, and yield requirements have completely reversed the cost curve for high-end memory. Future "price increases" will no longer be purely due to hoarding but will be underpinned by a permanent elevation in the physical cost structure.

"Fire and Ice" Between Consumer End and AI Data Centers

SanDisk's data center business revenue surged 103% quarter-over-quarter, while its consumer business conversely declined by 32%. This exposes a deeper concern: as AI monopolizes all advanced wafer capacity, end consumer electronics (smartphones, PCs), unable to absorb the high memory costs, are seeing some demand permanently eroded.

The Comeback of HDDs: From "Cold Storage" to "AI Warm Inference"

Seagate and Western Digital's HDD gross margins are nearing a staggering 55%-57%. Supporting this phenomenon is the advent of the Agentic AI era.

In multi-turn interactions, context caches (KV Cache) are being layered and placed extensively on HDDs to avoid GPU recomputation. High-capacity hard disk drives have forcefully transformed from "cost centers" for cold data archiving into "key enablers" for improving computational efficiency.

03. Hidden Worries Behind the Boom: Peak Capacity Battle and "Volume-Price Decoupling"

Although giants claim "supply tightness will persist beyond 2027," the frenzy in capital expenditures (CapEx) has already sown the seeds for future trouble:

Capital Expenditures (CapEx) Run Amok: SK Hynix's 2026 CapEx is hitting a high of 40 trillion KRW, with expansions accelerating at Yongin Fab1 and M15X; Micron's FY26 CapEx stands at a massive $27 billion. Launching an unprecedented wave of factory construction during the peak of industry profitability has historically been a precursor to the next supply glut cycle.

Rampant Profitability Relying Solely on "Price Hikes," Bit Shipment Growth Slows: Western Digital's Q4 hard drive bit shipment (Exabyte) growth has slowed from 30%+ to 22%, yet revenue skyrocketed by 44%.

When the core driver of explosive earnings growth becomes entirely "skyrocketing unit prices" rather than "a surge in absolute demand," the fragility of extremely high gross margins becomes starkly exposed. Once price support shows any marginal weakness, the retreat in profits will be extraordinarily sharp.

04. Conclusion: The Cycle Hasn't Disappeared, It Just Put on an AI Suit

The Microns of the world are trying to tell the market a new story—memory has transformed from a "strongly cyclical commodity" into a strategically scarce asset akin to "data infrastructure utility."

The narrative is perfect: AI-generated data has a "compound interest effect," data, once created, does not disappear; therefore, memory demand will grow perpetually.

But the capital market is always sober and cruel. The post-earnings stock plunge is smart money voting with its feet: they acknowledge AI has brought a historic, long runway for memory, but they are also acutely aware that when valuations and earnings expectations are pushed to their zenith, the margin of safety has vanished.

Keep the music playing, keep dancing? Perhaps the giants in the ballroom are still intoxicated, but funds on the sidelines have already begun quietly exiting.

AI isn't over; it's just that money is starting to move elsewhere.

Disclaimer: The copyright of this article belongs to the investment research team of Beijing Glonhui Investment Advisory Co., Ltd. (Duan Yuehan: A0160625050003). This report is prepared based on independent, objective, fair, and prudent principles. Information is sourced from publicly available materials and legally, reasonably, and appropriately collected, summarized, and edited.

The stock market carries risks, and investment requires caution. Any investment suggestions herein do not constitute a basis for your trading decisions. You must make independent investment decisions and bear your own risks. Any unit or individual who publishes, copies, disseminates, or network-publishes or reprints this article without the company's permission will be deemed as infringement, and the company will pursue legal liability.

This article is from the WeChat public account "Gelonghui Financial Hotspots" (ID: glh_finance), author: Gelonghui editor.

Related Questions

QDespite reporting record-breaking financial performance, why did semiconductor memory stocks like Western Digital and SanDisk experience significant price drops?

AThe stock prices plummeted because the stellar results had already been fully anticipated and priced in by the market. The subsequent quarterly guidance, even if only slightly conservative, was perceived as falling short of the extremely high expectations. This triggered profit-taking, as the positive news was considered already reflected in the valuations ('sell the news').

QWhat are the four 'abnormal' or unprecedented signals identified in the memory market reports that break from the traditional cycle?

A1. Financialized Pricing: Customers are paying massive 'interest-free deposits' to secure future supply (like Micron's $18B and SanDisk's $16.5B). 2. Inversion of Moore's Law: The cost per bit for advanced DRAM (e.g., HBM4, DDR6) is increasing due to complex 3D packaging. 3. Divergence Between Consumer & AI: Data center (AI-driven) revenue is surging while consumer electronics (phones, PCs) is declining due to high memory costs. 4. HDD's AI Revival: Hard Disk Drives are becoming crucial for AI 'warm inference,' improving compute efficiency by storing KV Cache, and achieving ~55% margins.

QAccording to the article, what is a major hidden risk behind the current profitability surge in the memory sector?

AThe major risk is a potential future supply glut driven by uncontrolled capital expenditure (CapEx). Companies like SK Hynix and Micron are investing massively in new capacity during the peak of the profit cycle. This, coupled with slowing bit shipment growth and a heavy reliance on price increases rather than volume demand, makes the current high-margin structure vulnerable. Any future price correction could lead to a sharp profit contraction.

QHow is the role of Hard Disk Drives (HDD) changing in the AI era, according to the report on Seagate and Western Digital?

AHDDs are transforming from a 'cold storage' cost center into a key enabler for AI computational efficiency. In the Agentic AI era, they are used to store context caches (KV Cache) for multi-turn interactions. This allows GPUs to avoid recalculations, making high-capacity HDDs essential for 'AI warm inference' and driving their gross margins to impressive levels of 55%-57%.

QWhat is the new narrative that memory companies are trying to sell to the market, and how is the market reacting to it?

AMemory companies are promoting a narrative that storage has transformed from a cyclical commodity into a strategically scarce 'data infrastructure utility' due to AI. They argue that AI-generated data has a 'compound interest' effect and creates perpetual demand. However, the market's reaction (the sharp stock sell-off) shows that while investors acknowledge AI's long-term potential ('long slope'), they believe current valuations have become excessive, leaving no margin of safety, and are therefore taking profits.

Related Reads

Anthropic, OpenAI, and the U.S. Treasury on Slowing AI: Three Positions and One Shared Fear

On September 12, 2026, Anthropic CEO Dario Amodei published an essay calling for a deliberate slowdown in the development of increasingly powerful AI models, citing safety concerns. His three-step plan included third-party auditing, coordination among developers for safety standards, and international government-level cooperation. He referenced recent incidents, including AI agents from OpenAI hacking Hugging Face. The U.S. Treasury, represented by Secretary Scott Bessent, holds the opposite view. On September 8, he argued that the U.S. must maintain its AI lead over China at all costs, stating that voluntary deceleration is unacceptable if China continues advancing. Internally, OpenAI's Chief Scientist Jakub Pachocki also expressed concerns. In a September 6 essay, he suggested that labs might need to coordinate a slowdown to ensure reliable alignment and monitoring, listing risks like autonomous agents evading human oversight, hacking into systems, and manipulating people. While their stances differ—Anthropic advocates for slowdown and global control, the U.S. Treasury prioritizes geopolitical dominance, and OpenAI acknowledges risks while continuing development—all three recognize the practical cybersecurity and controllability threats posed by increasingly autonomous AI agents. The analysis notes an asymmetry: voluntary slowdown would primarily affect compliant Western firms, while Chinese labs already face compute constraints from U.S. export restrictions. Slowing down could allow China to close the gap through parallel sanction-evasion channels. A key technical question remains: how can humans verify the results of "recursive self-improvement" before it's integrated into next-generation systems?

cryptonews.ru5m ago

Anthropic, OpenAI, and the U.S. Treasury on Slowing AI: Three Positions and One Shared Fear

cryptonews.ru5m ago

25 Fields Medal Laureates Warn: The AI Race Is Harming Mathematics

On September 11, 2026, 25 Fields Medal laureates issued an open statement titled "The Deep Mismatch Between AI and the Aims of Mathematics." They warn that the tech industry's race to use unsolved mathematical problems as benchmarks for AI performance is harming mathematics itself. The mathematicians argue that the core aim of mathematics is conceptual understanding, not merely generating true/false statements. The rapid, mass production of solutions by AI, often published hastily without proper methodology, attribution, or integration into mathematical canon, risks destroying the intellectual soil where new ideas grow. It threatens the human chain of understanding and the development of the ability to ask new questions. The immediate trigger was OpenAI's September 8 announcement. Using 10,000 AI agents over 88 hours, its internal system reportedly found a proof that Navier-Stokes equations can develop a finite-time singularity. While OpenAI stated it is not claiming the Clay Millennium Prize, similar AI-assisted results on related equations were announced by mathematicians from NYU and Anthropic. The signatories, a historic group including Artur Avila, Terence Tao, Maryna Viazovska, and Peter Scholze, acknowledge AI's potential to accelerate genuine understanding. However, they stress that whether the impact is beneficial or destructive depends on human decisions controlling the technology. They call for urgent discussion within the mathematical community and with AI developers. The conflict highlights a widening gap between the speed of AI-generated results and the traditional, slower pace of scientific verification and knowledge integration. In the broader context of the corporate race toward Artificial General Intelligence (AGI), mathematical breakthroughs risk becoming showcases for investors rather than contributions to enduring human knowledge.

cryptonews.ru2h ago

25 Fields Medal Laureates Warn: The AI Race Is Harming Mathematics

cryptonews.ru2h ago

Trading

Spot
活动图片