Author: Byron Gilliam, blockworks
Compiled by: Deep Tide TechFlow
Deep Tide Digest: Bitcoin supporters often label fractional-reserve banking as a Ponzi scheme, claiming that any bank run, no matter how healthy the bank, will lead to its collapse. However, a new study analyzing numerous historical bank run events found that most runs fizzle out before posing any real threat to the bank. This is a rebuttal that investors who use banking fragility as a crypto narrative must confront.
"You're thinking of this place all wrong. As if I had the money back in a safe." (George Bailey on fractional-reserve banking)
The fundamental promise of banking is that everyone can get their money back at any time, as long as they don't all ask for it at the same time.
That's what George Bailey taught us.
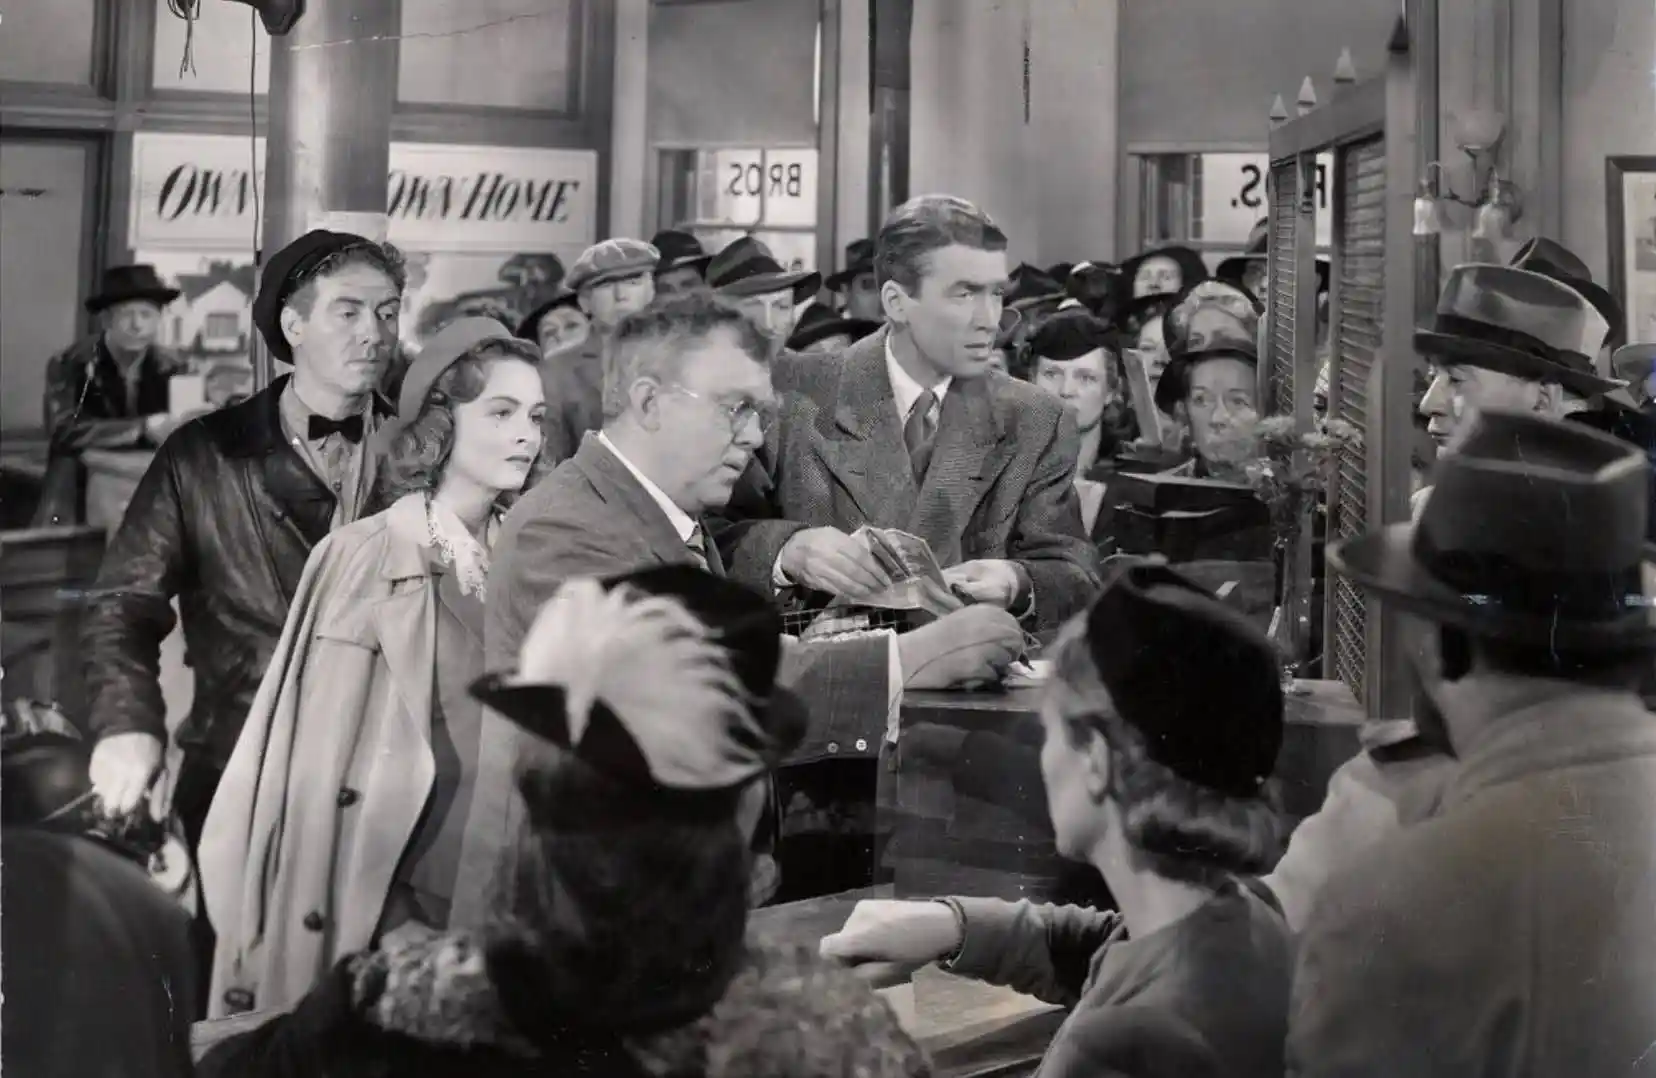
"You're thinking of this place all wrong. As if I had the money back in a safe," he told the customers making a run on the Bailey Brothers Building & Loan. "The money's not here. Your money's in Joe's house, right next to yours. And in the Kennedy house, and Mrs. Macklin's house, and a hundred others."
"You're lending them the money to build, and then, they're going to pay it back to you as best they can," he explained.
The anxious clients were not immediately reassured. George had to use his own $2,000 to fend off the run. Even then, the bank wasn't truly saved until the end of the film: friends and clients donated enough money to cover the $8,000 shortfall on the bank's balance sheet.
The Austrian School economist Murray Rothbard would say, let Bailey Bros. fail. "Fractional reserve banking is a scam, a Ponzi scheme, a fraud," he once wrote.
He believed banks could perpetrate this fraud because bankers like George Bailey misrepresented how they were able to make so many loans.
"Because we're used to thinking the bank just takes our money and lends it out," Rothbard explained in a speech, "it's very difficult to shift gears and realize that the bank is engaged in legalized counterfeiting."
In other words, if people truly understood how fractional reserve banking works—how banks create money "out of thin air"—everyone would demand their money back at once. Even the best banks would fail.
This pessimistic view of banks seemed to have academic backing. Economists Douglas Diamond and Philip Dybvig authored a classic study on the fragility of fractional-reserve banking: "Bank Runs, Deposit Insurance, and Liquidity."
This research formalized Rothbard's intuition: banks that finance long-term loans with demand deposits are at risk of being dragged down by a run, even if their assets are healthy.
Thus, fears of bank failure can be self-fulfilling: "During a run, depositors rush to withdraw their deposits because they expect the bank to fail," the authors explained. "In fact, the sudden withdrawals force the bank to liquidate many of its assets at a loss and eventually to fail."
"This need not have anything to do with the bank's fundamentals," they added. Instead, "anything that causes [depositors] to anticipate a run will lead to a run."
"Even 'healthy' banks can fail."
Diamond and Dybvig arrived at this troubling conclusion primarily through a theoretical model based on mathematics and game theory.
A new study suggests this model does not reflect reality.
Every recorded run event, scraped by a large language model from newspaper reports, is logged on a website detailing why the run started and how it was resolved.
The surprising finding is that most runs fizzle out on their own before threatening the bank. The authors found: "There are more runs that do not lead to a bank failure than runs that do."
This is inconsistent with the expectations of the Diamond-Dybvig self-fulfilling model.
Even among banks with "very weak" fundamentals, only 59% failed after experiencing a run.
I imagine Rothbard would have expected that number to be 100%.
Meanwhile, banks with the strongest fundamentals "rarely fail," even when facing a run.
The authors' conclusion? "This pattern casts doubt on the strong view that liquidity problems alone can trigger serious financial distress."
I think that's their polite way of saying Diamond, Dybvig, Rothbard, gold bugs, and Bitcoiners are all wrong about fractional-reserve banking.
A Mountain of Cases
Diamond and Dybvig were right about at least one thing: "Bank runs in our model are caused by a shift in expectations," they noted, "and the expectations can depend on almost anything."
A random scroll through the Bank Runs database turns up some excellent examples.
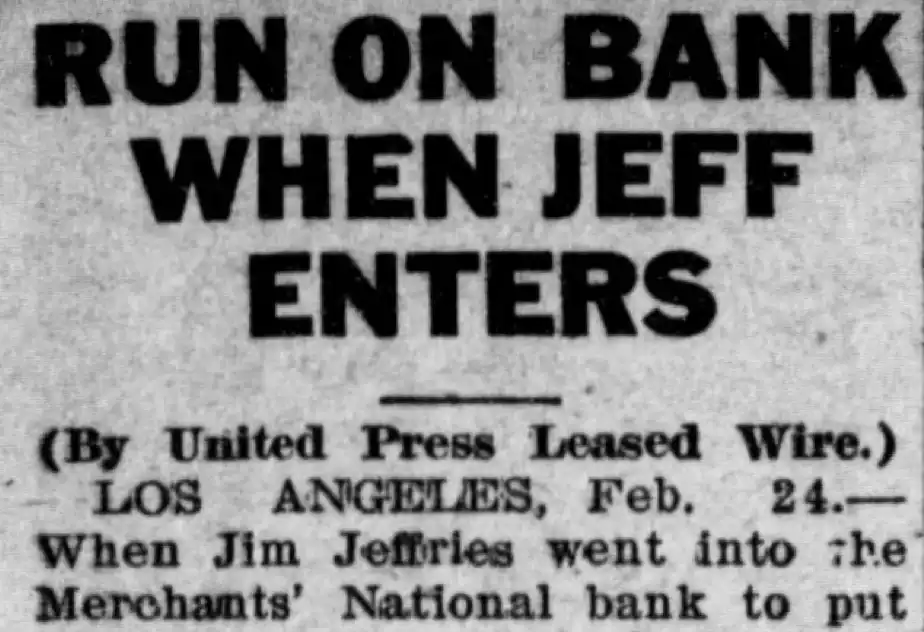
In 1910, a run on the Merchants National Bank of Los Angeles started when boxer Jim Jeffries visited the bank, drawing a crowd of fight fans. The newspaper reported: "Dozens of depositors, thinking something was wrong, began cashing in their deposits. Not until the fighter departed were the frightened customers reassured."
It turned out Jeffries was just opening an account to deposit part of his championship prize money.
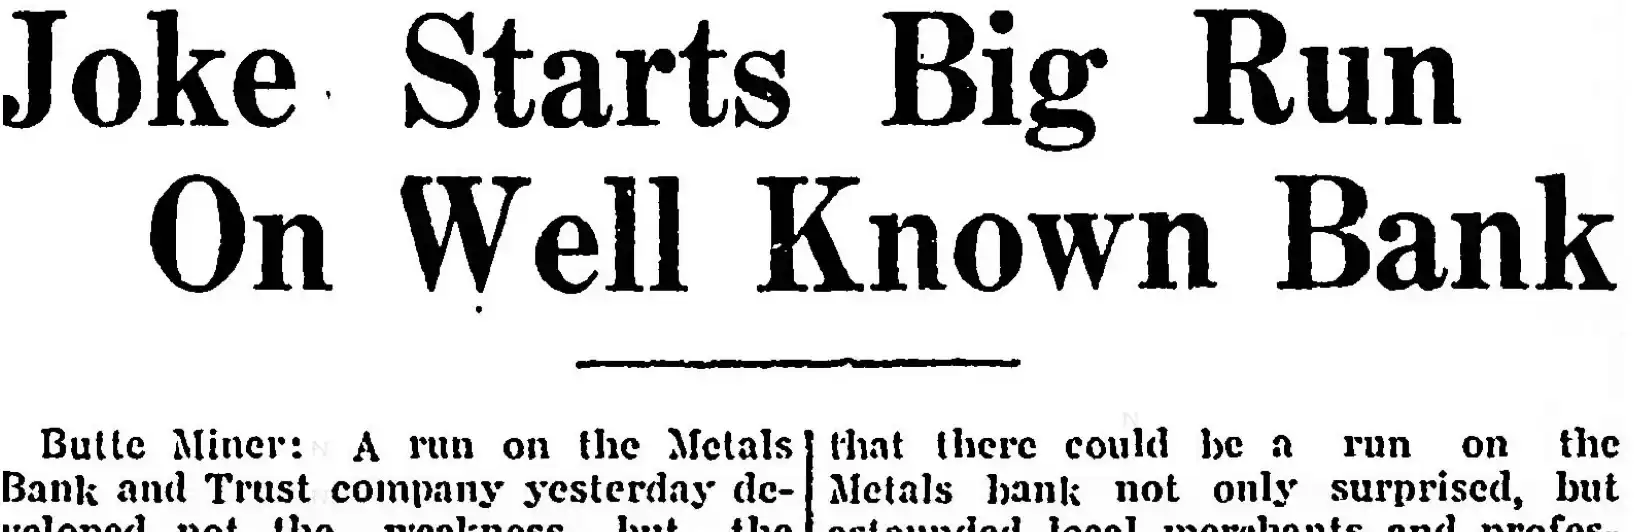
In 1924, a run on the Metals Bank & Trust Company in Butte, Montana, started when someone overheard a joking bet that the bank wouldn't open the next day. The newspaper reported the bank stayed open four hours past its usual closing time to satisfy withdrawals, "until darkness made it unsafe to continue paying depositors."
The joke was that the bank would indeed be closed the next day—for Lincoln's Birthday.
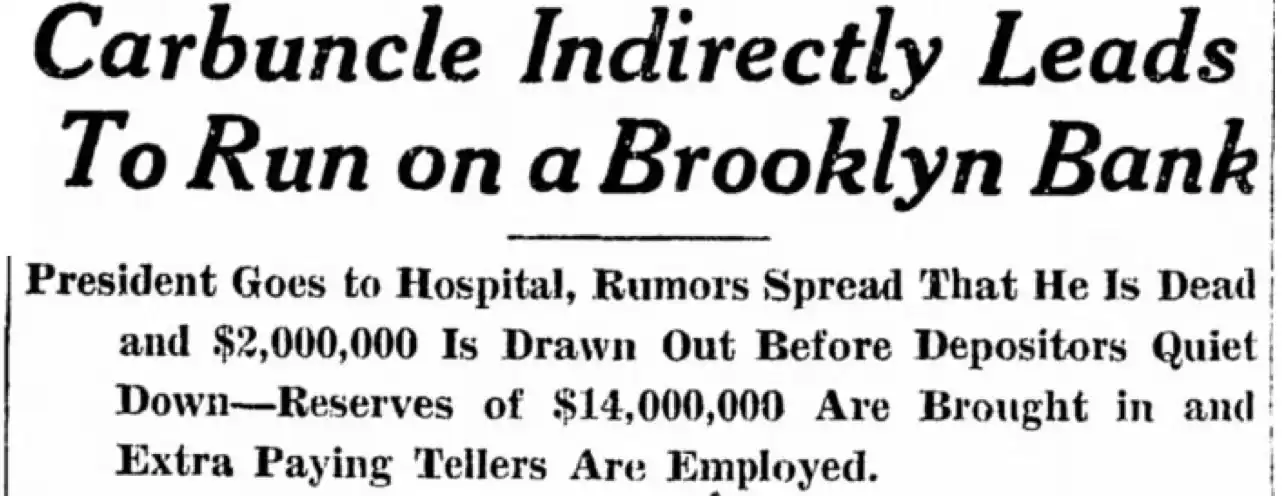
In 1929, a run on the Bay Ridge Savings Bank in Brooklyn, New York, started with a rumor that the bank's president had died. Fortunately, the newspaper reported, the bank "was forewarned of the false report" and thus had time to prepare $14 million in cash to meet withdrawals.
The truth was, the president had gone to Connecticut to have a carbuncle removed from his neck. (He survived the operation.)
Again, these are just random samples from the database.
But the peaceful resolution of these runs seems to refute the strongest interpretation of the Diamond-Dybvig theory: it turns out bank runs are rarely self-fulfilling.
Sometimes, however, they are.
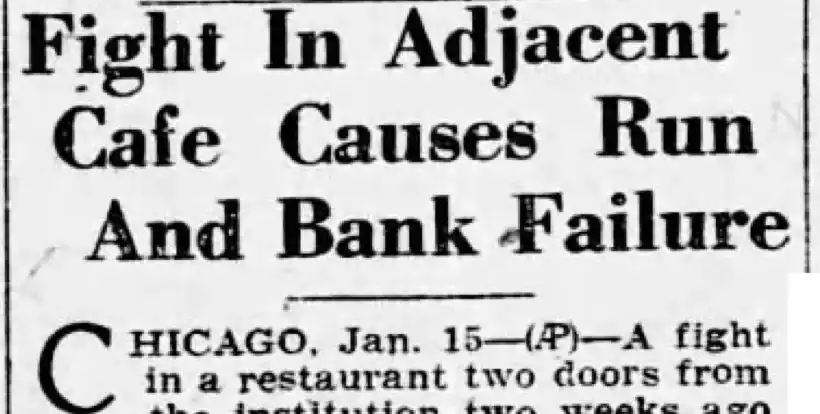
In 1930, a run on the Independence State Bank of Chicago started with a fight two doors down. The newspaper reported: "A patrol wagon answering a restaurant call stopping in front of the bank building started rumors that the bank was being raided." Somehow, over $1.6 million was withdrawn from the bank's $5.6 million in deposits, which surely exhausted the bank's liquid assets because state officials felt compelled to close it.
The Bank Runs website doesn't say whether Independence Bank's balance sheet was fundamentally sound. But the authors' research indicates that if it were, the bank almost certainly would have survived.
In many cases, surviving a run required only a public display of cash.
For example, a 1907 run was stopped by "the liberal exhibition on counters of bills and cash to show depositors."
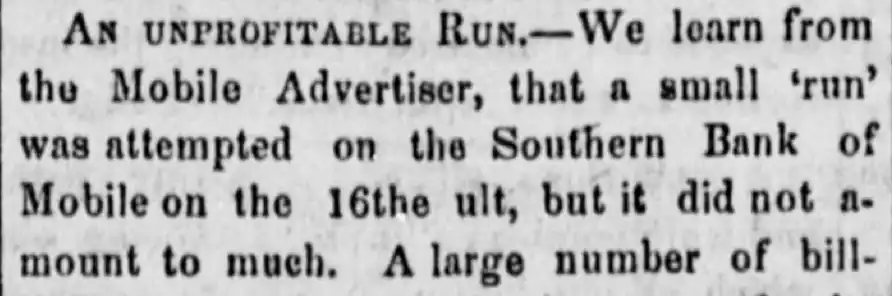
In 1857, an "unprofitable run" on an Alabama bank was halted after depositors saw tellers' desks piled high with "a Malakhov of gold and a Redan of silver." (Malakhov and Redan were famous Russian fortresses.)
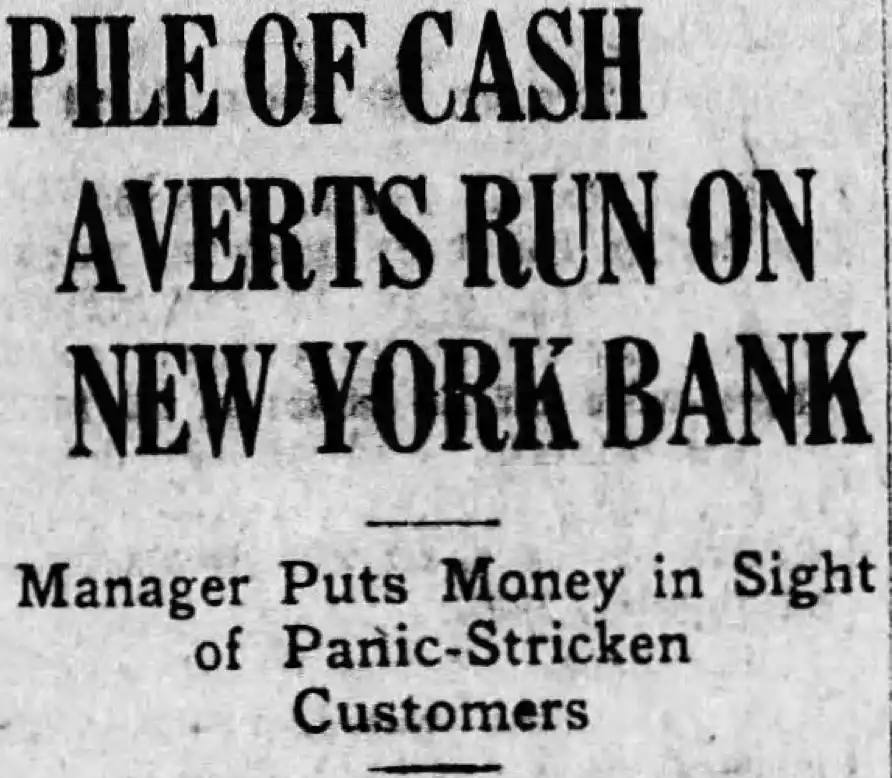
In 1924, a manager at a Brooklyn bank stopped a run by piling banknotes of denominations up to $1,000 in the bank's front window, "carelessly heaped in a large pile" for all to see.
Do bank customers understand that no matter how high the pile of cash, it wouldn't be enough to pay everyone if they all wanted their money at once?
I suspect they do.
(Byron Gilliam)