Written by: Edgy
Compiled by: Chopper, Foresight News
I am searching for cryptocurrencies with valuation advantages. I set three screening criteria for tokens ranked in the top 300 by market capitalization: revenue growth, valuation lower than industry peers, and token price not yet reflecting the improvement in fundamentals.
In the end, only two projects met all the standards, and they share common characteristics; the projects that were filtered out might be more worthy of in-depth investigation. Here are the conclusions of this research.
Explanation of Screening Rules
The goal of this screening is to identify projects that simultaneously meet all three conditions:
- Lower valuation compared to peers in the same sector
- Revenue growth rate outperforms the market average
- Token price has not yet priced in the positive fundamentals
Using CoinGecko prices and DeFiLlama revenue as benchmarks, I compared data from the past 30 days with the previous 60 days. Then, I asked Claude to assist me with the analysis.
A key adjustment was made in this analysis: ranking is based on the protocol's actual retained revenue, not total fees. Fees are the total amount paid by users, while revenue is the profit actually retained by the protocol.
Take Jito as an example: for every $100 in fees generated, the protocol only retains about $6, with the vast majority distributed as MEV rewards to validators.
If valued based on total fees, Jito's P/E ratio is only 4.5x, appearing extremely cost-effective; but when calculated based on the protocol's actual retained revenue, the valuation is as high as 73x.
Lido similarly retains only about 6% of fees, and Uniswap's retention ratio is 8%.
If judged solely by fees, the "undervalued opportunities" you find are not real.
How 300 Tokens Were Reduced to Just 2
First round of preliminary screening, filtering down to 38 targets with valid statistical data:
- Initial sample: 300 tokens
- Among them, DeFiLlama can query revenue data: 117
- Excluding public chain projects and overly small targets, filtering down to projects where the protocol can retain revenue: 38 remaining
Projects like Morpho, Ondo, Celestia, The Graph, EigenCloud were all excluded. While these projects generate fees, the profits do not flow back to the token itself.
Subsequently, three screening thresholds were applied sequentially, comparing each project to the median Fully Diluted Valuation (FDV) to Annualized Revenue in its own sector (Trading, Lending, Staking, and Others):
- Valuation lower than peers → 18 remaining
- Revenue growth higher than sector median → 9 remaining
- Token price increase lags sector median → 3 remaining
Adding a stress test to eliminate targets with abnormal one-day spike revenue, only 2 remained in the end.
The industry median level is an average 18% increase in project revenue and a 25% average increase in token price. A target must have revenue growth exceeding 18% and a token price increase below 25% to qualify.
The Bias from Fully Diluted Valuation (FDV)
Using FDV instead of circulating market cap for valuation directly eliminated many projects with solid fundamentals. Hyperliquid is the most typical example: calculated based on circulating market cap, the revenue multiple is 28x; but using FDV calculation pushes the valuation to 120x, because the circulating token supply is only a quarter of the total supply.
This criterion might not be fair to HYPE, but this screening uniformly applies this rule.
Results
Cheap valuation, business growth, but price already fully reflects value.
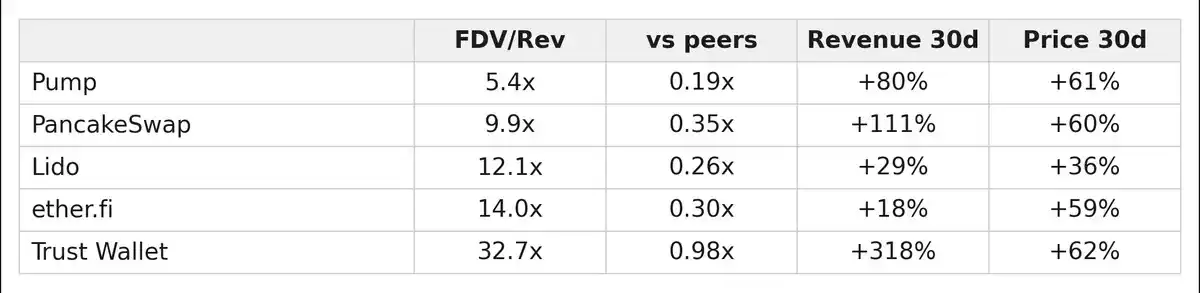
Pump remains the project with the strongest business model in this screening. 30-day revenue of $57 million, valuation less than 6x; revenue up 80%, token price up 61%. The market has already priced it fully, no undervaluation opportunity exists. The market pricing for this type of token is efficiently reasonable.
Low valuation, but out of market favor, business itself is no longer growing.
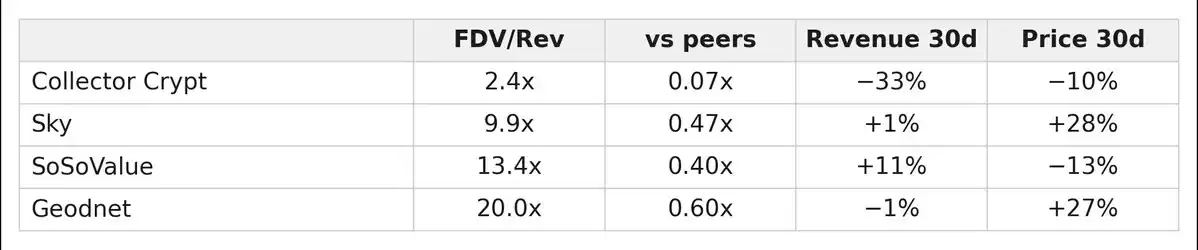
Value trap zone, low price does not equal undervalued. Collector Crypt revenue multiple is only 2.4x, the lowest valuation among the top 300 tokens, but its revenue dropped by one-third.
Business growth, low market attention, but valuation is not cheap.
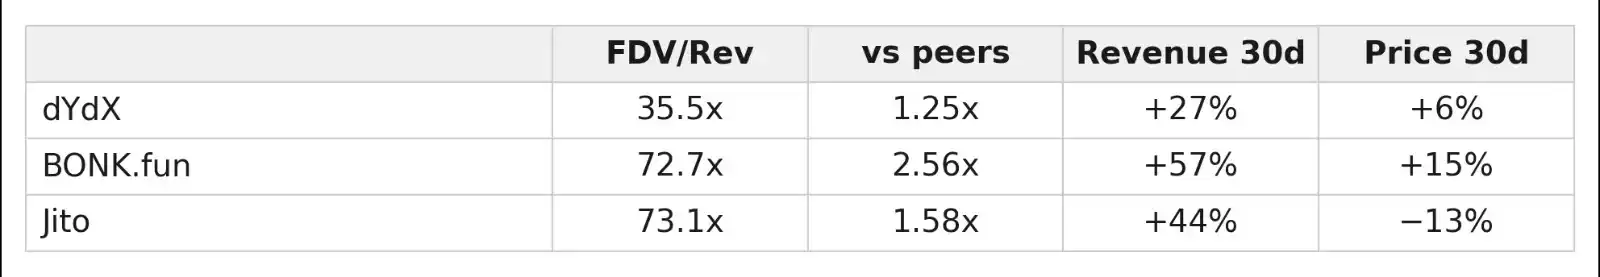
Revenue continues to rise, token price is flat or even falling, seemingly a perfect deployment opportunity on the surface. But compared horizontally to competitors, their valuations are actually high.
If looking only at fee data, Jito can easily mislead investors: revenue up 44%, token price down 13%, fee-based valuation is only 4.5x. Seems like a perfect opportunity, but when converted to real retained revenue, the valuation reaches 73x.
Bonk has another issue. After removing the spike data from the last three days, the 57% revenue growth directly turns into a negative 17% decline. This growth is likely just a short-term pulse effect brought by the Solana market trend.
Meeting all three conditions.
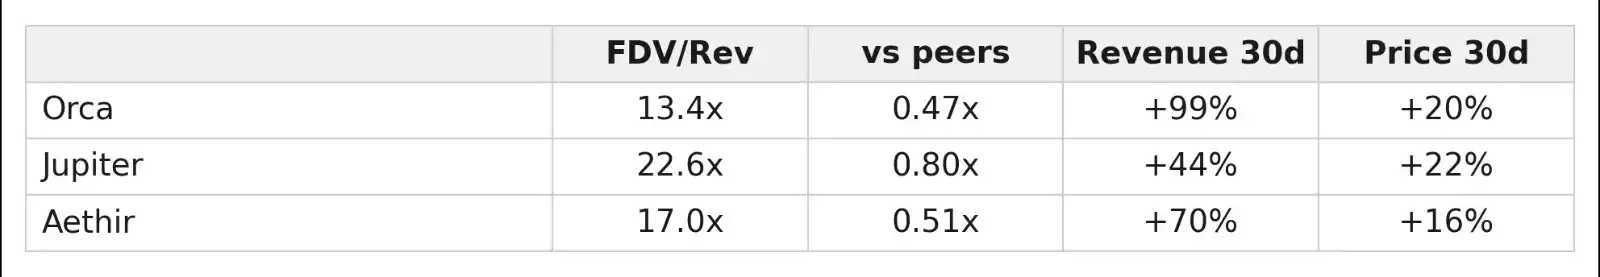
Aethir failed the revenue stability stress test, with 65% of monthly revenue concentrated in a single-day spike. The underlying cause has not been deeply investigated yet, preliminary data suggests high risk.
Finally, Orca and Jupiter remained, both belonging to Solana ecosystem decentralized exchanges.
The Objective Variable Brought by the Solana Trend
The background must be stated objectively here: SOL increased by 42% that month, part of the exchange revenue growth came from the lagging effect of the Solana bull market, but there are also independent fundamental drivers. Both projects' revenue growth rates outperformed SOL itself, yet their token price increases lagged far behind the public chain.
Jupiter has a more mature business model:
- 30-day revenue $6.4 million, revenue growth 44%
- Fee retention ratio 34%, performing outstandingly in profit quality within this screening sample
- Token price increase 22%, sector median is 25%, meeting the "price lag" screening condition by only a slight margin
Orca has a lower valuation and is a smaller project:
- Monthly revenue $700k, ranked 293rd by market cap
- Revenue doubled, and the growth was spread throughout the month rather than concentrated overnight, indicating genuine growth; the downside is the relatively small project scale.
Meteora is worth mentioning. It narrowly missed the growth target by 0.04 percentage points. Revenue grew 18.33%, target value was 18.37%, P/E ratio 7.9x.
Positioning and Limitations of This Screening List
This content does not constitute any buying advice. I will use another complete evaluation system to deeply investigate truly undervalued targets; subsequent comprehensive research across more dimensions is still required.
This screening selected projects with at least 60 days of revenue history, so Robinhood Chain tokens launched relatively recently are not within the statistical scope.
The core significance of this list lies in screening out crypto projects whose businesses are growing, but whose token prices have not yet reflected the upward potential.